Key takeaways
- The short answer: the best-known mezzanine lenders are credit managers such as HPS Investment Partners, Audax Private Debt and Churchill Asset Management, plus specialists such as Northcreek Mezzanine and Nordic Mezzanine. Private Equity List lists 59 firms that provide mezzanine debt.
- Where they are: 25 of the 59 are in the US and 20 in Europe, 6 of them in the UK.
- Contacts: 58 of the 59 have investment-team contacts in their profiles, 535 people in total.
- Cheque size: the most common bracket is $10–50M (24 firms). 9 firms write $100M or more.
- Biggest funds: HPS Mezzanine Partners 2019 ($11B), Schroders Capital's Junior Infrastructure Debt Europe III ($2B) and Audax Mezzanine Fund V ($1.85B).
- What it costs: lenders target 12–20% a year, paid as cash interest, interest added to the loan and often warrants. It is repaid after the senior bank loan and before the owners' equity.
 United States | |
|---|---|
 United Kingdom | |
 France | |
 Canada | |
 Germany | |
 Croatia | |
 Mexico | |
 Hong Kong |
Source: Private Equity List database
| $10–50M | 24 | 40.7% |
|---|---|---|
| $1–5M | 11 | 18.6% |
| $50–100M | 10 | 16.9% |
| $100M+ | 9 | 15.3% |
| Under $1M | 3 | 5.1% |
| $5–10M | 2 | 3.4% |
Source: Private Equity List database
What is mezzanine financing: debt between the bank loan and equity
Mezzanine debt: a loan that ranks below senior debt and above equity. If the company fails, senior lenders are repaid first, mezzanine lenders next, owners last.
Also called: subordinated debt, junior debt or junior capital. Funds that do it are mezzanine funds or junior capital funds.
How it pays: cash interest, interest added to the loan instead of paid (PIK), and often warrants that give the lender a small equity stake.
Why borrowers take it: it fills the gap when the bank will not lend enough and the owners do not want to sell more of the company.
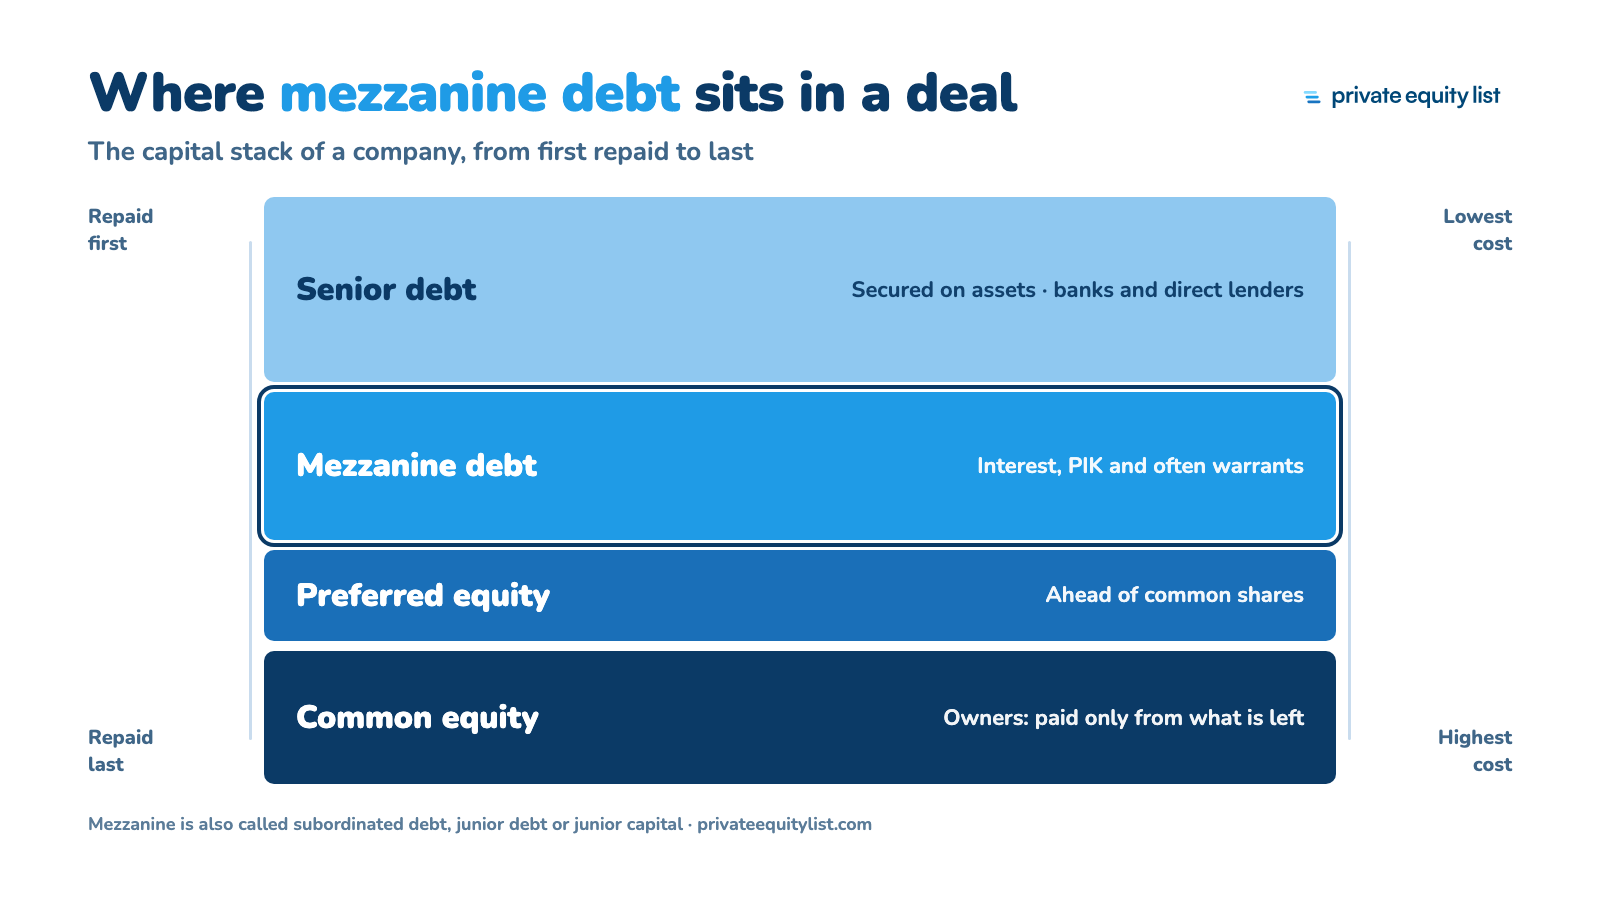
How much mezzanine debt costs: 12–20% a year
Total return: mezzanine lenders target 12–20% a year, more than ordinary bank debt (Corporate Finance Institute; CAIS). Wall Street Prep puts the blended yield at around 15–20% or more.
How it is paid: part cash interest, part PIK interest that is added to the loan instead of paid, and often warrants. A textbook deal: 10% cash interest, 3% PIK and warrants for 4% of the company (Wikipedia).
Term: privately negotiated and longer than most bank loans, up to 8 years (CAIS).
Repaying early: usually not allowed in the first years, and after that only with a fee (Wall Street Prep).
Share of a buyout: in a typical leveraged buyout mezzanine is 10–20% of the capital, senior debt 30–40% and equity 30–50% (Wall Street Prep, Oaktree sample).
Biggest mezzanine and junior capital funds: HPS, Schroders and Audax
 HPS Investment Partners runs the largest mezzanine fund in Private Equity List, HPS Mezzanine Partners 2019, at about $11B. Mezzanine is one of its credit strategies, next to leveraged loans, high-yield bonds and asset-based leasing.
 Schroders Capital launched its third Junior Infrastructure Debt Europe fund in 2025, sized at $2B. The money goes into junior loans to European infrastructure.
 Audax Private Debt raised $1.85B for Audax Mezzanine Fund V. It lends senior and junior debt to middle-market companies and co-invests equity.
 Sentinel Capital Partners runs Sentinel Junior Capital II ($835M) next to its buyout funds.
 Churchill Asset Management raised $737M for Junior Capital Opportunities Fund II. It finances US middle-market private equity deals with first lien, unitranche, second lien and mezzanine loans.
 ActoMezz, co-managed by Andera Partners in Paris, raised $562M for Acto Mezzanine IV. It provides mezzanine and minority equity to small and mid-sized companies.
 Northcreek Mezzanine in Cincinnati launched Fund V in December 2024, recorded at $250M. It is a Small Business Investment Company (SBIC), a fund licensed and partly financed by the US Small Business Administration.
 Star Mountain Capital closed its second SBIC fund at $286M in February 2026. It lends senior and junior debt to lower middle-market companies.
Mezzanine lenders to know in the US and Europe
| Firm | Headquarters | Cheque size | What it provides |
|---|---|---|---|
| HPS Investment Partners | New York | $10–50M | Mezzanine, leveraged loans and other credit across the capital structure |
| Audax Private Debt | New York | $100M+ | Senior secured and junior debt to middle-market companies |
| Churchill Asset Management | New York | $100M+ | First lien, unitranche, second lien and mezzanine loans for private equity deals |
 Antares Capital | Chicago | $100M+ | Senior secured loans, mezzanine debt and structured equity |
| Star Mountain Capital | New York | $100M+ | Senior and junior debt to lower middle-market companies |
 Brightwood Capital Advisors | New York | $10–50M | First and second lien loans, unitranche and mezzanine |
 Capital Southwest | Dallas | $10–50M | First lien, second lien and subordinated debt, listed on Nasdaq as a BDC |
 Charter Capital Partners | Grand Rapids | $100M+ | Junior capital for lower middle-market companies in the Great Lakes region |
| Northcreek Mezzanine | Cincinnati | $50–100M | Mezzanine for lower middle-market companies, as an SBIC |
 Source Capital | Atlanta | $10–50M | Flexible debt and equity for lower middle-market companies |
 Park Square Capital | London | $100M+ | Senior and subordinated debt to European and US companies |
 Nordic Mezzanine | London | $50–100M | Mezzanine for buyouts, growth and restructurings, backed by Nordic institutions |
 Indigo Capital | London | $1–5M | Mezzanine and junior capital for privately owned European companies |
 CAPZA | Paris | $1–5M | Growth capital, mezzanine and senior loans for small and mid-caps |
 Siparex | Paris | $10–50M | Equity and mezzanine for French and European companies |
 VR Equitypartner | Frankfurt | $1–5M | Majority and minority stakes plus mezzanine, owned by DZ BANK |
 Polaris Private Equity | Copenhagen | $50–100M | Junior capital and minority stakes through its Flexible Capital strategy |
 CVI | Warsaw | $10–50M | Senior, junior, unitranche and mezzanine debt in Central Europe |
All 59 mezzanine lenders in Private Equity List, by region
Every firm below provides mezzanine, junior or subordinated debt, checked against its profile. Cheque size is the range on the profile; «Listed as» shows where the firm sits in the investor lists, so you know which list to filter.
Mezzanine lenders in the United States
25 lenders, nine of them in New York. Six write cheques of $100M or more: Antares Capital, Audax Private Debt, Charter Capital Partners, Churchill Asset Management, Star Mountain Capital and TA Associates. Ten write $10–50M, the most common size.
| Firm | City | Cheque size | Listed as |
|---|---|---|---|
| Antares Capital | Chicago | $100M+ | Venture capital, Private equity |
| Audax Private Debt | New York | $100M+ | Private equity, Debt fund |
| Charter Capital Partners | Grand Rapids | $100M+ | Private equity |
| Churchill Asset Management | New York | $100M+ | Debt fund, Private equity |
| Star Mountain Capital | New York | $100M+ | Debt fund, Venture capital |
 TA Associates | Boston | $100M+ | Private equity |
 Gryphon Investors | San Francisco | $50–100M | Private equity |
 Harbor Group International | Norfolk | $50–100M | Private equity, Fund of funds |
 LBC Credit Partners | Miami | $50–100M | Private equity, Debt fund |
| Northcreek Mezzanine | Cincinnati | $50–100M | Private equity, Debt fund |
| Brightwood Capital Advisors | New York | $10–50M | Private equity, Debt fund |
| Capital Southwest | Dallas | $10–50M | Private equity, Debt fund |
 CM Equity Partners | New York | $10–50M | Private equity |
| HPS Investment Partners | New York | $10–50M | Private equity, Debt fund |
 Independent Bankers Capital Funds | Dallas | $10–50M | Private equity |
| Sentinel Capital Partners | New York | $10–50M | Private equity |
| Source Capital | Atlanta | $10–50M | Venture capital, Private equity |
 The Firmament Group | New York | $10–50M | Private equity, Debt fund |
| Trinity Capital | Phoenix | $10–50M | Private equity, Debt fund |
 Veronis Suhler Stevenson | New York | $10–50M | Private equity, Venture capital |
 Breakaway Capital | Los Angeles | $5–10M | Private equity, Fund of funds |
 CVF Capital Partners | Davis | $5–10M | Private equity, Venture capital |
 AV Ventures | Washington | $1–5M | Private equity, Venture capital |
 Bayview Asset Management | Coral Gables | $1–5M | Private equity, Venture capital |
| Founders First Capital Partners | Omaha | Under $1M | Private equity, Venture capital |
Mezzanine lenders in the UK
Six lenders, all in London. Park Square Capital writes the largest cheques, $100M or more. Nordic Mezzanine and Standard Chartered Private Equity write $50–100M, Schroders Capital $10–50M, and 2b Capital and Indigo Capital $1–5M for smaller companies.
| Firm | City | Cheque size | Listed as |
|---|---|---|---|
| Park Square Capital | London | $100M+ | Private equity, Debt fund |
| Nordic Mezzanine | London | $50–100M | Private equity |
 Standard Chartered Private Equity | London | $50–100M | Private equity |
| Schroders Capital | London | $10–50M | Private equity, Debt fund |
 2b Capital | London | $1–5M | Private equity, Venture capital |
| Indigo Capital | London | $1–5M | Private equity |
Mezzanine lenders in Europe
14 lenders in 10 countries. France has three (ActoMezz, CAPZA and Siparex), Croatia and Germany two each. Eight of the 14 write $10–50M.
| Firm | City | Cheque size | Listed as |
|---|---|---|---|
 Mezzanine Partners | Zagreb | $50–100M | Private equity, Debt fund |
| Polaris Private Equity | Copenhagen | $50–100M | Private equity, Venture capital |
 aws Mittelstandsfonds | Vienna | $10–50M | Private equity, Venture capital |
 BE Beteiligungen Fonds | Cologne | $10–50M | Private equity, Venture capital |
 BPM Capital | Tallinn | $10–50M | Private equity |
| CVI | Warsaw | $10–50M | Private equity |
 Oxy Capital | Lisbon | $10–50M | Private equity, Debt fund |
 Pentahold | Zaventem | $10–50M | Private equity |
 Silverline Capital | Sofia | $10–50M | Private equity, Debt fund |
| Siparex | Paris | $10–50M | Private equity, Debt fund |
| ActoMezz | Paris | $1–5M | Private equity |
| CAPZA | Paris | $1–5M | Private equity |
 Hybrid Capital Partners | Zagreb | $1–5M | Private equity, Debt fund |
| VR Equitypartner | Frankfurt am Main | $1–5M | Private equity |
Mezzanine lenders in Asia, Canada, Latin America and the Middle East
14 lenders from Toronto to Hong Kong. Canada, Mexico and Hong Kong have two each; the rest are in China, India, Israel, Kuwait, the UAE, Australia and Kyrgyzstan.
| Firm | City | Cheque size | Listed as |
|---|---|---|---|
 FIMI Opportunity Funds | Tel Aviv, Israel | $100M+ | Private equity |
 Gresham Private Equity | Sydney, Australia | $100M+ | Private equity |
| CLSA Capital Partners | Hong Kong, Hong Kong | $50–100M | Private equity, Debt fund |
 NBK Capital Equity | Dubai, United Arab Emirates | $50–100M | Private equity |
 China Development Bank Capital | Beijing, China | $10–50M | Private equity |
 EdgeStone Capital Partners | Toronto, Canada | $10–50M | Private equity, Venture capital |
 Markab Capital | Kuwait City, Kuwait | $10–50M | Private equity |
 Motilal Oswal Private Equity | Mumbai, India | $10–50M | Private equity |
 Nexxus Capital | Mexico City, Mexico | $10–50M | Private equity, Debt fund |
| Adobe Capital | — | $1–5M | Private equity |
 Alsis Funds | Mexico City, Mexico | $1–5M | Private equity |
 McKenna Gale Capital | Toronto, Canada | $1–5M | Private equity |
 CDH Investments | Hong Kong, Hong Kong | Under $1M | Venture capital, Private equity |
 Highland Capital | Bishkek, Kyrgyzstan | Under $1M | Private equity |
Mezzanine debt vs senior debt vs equity
| Senior debt | Mezzanine debt | Equity | |
|---|---|---|---|
| Repaid | First | After senior debt | Last, if value is left |
| Security | Secured on the company's assets | Usually unsecured or second in line | None |
| Cost to the company | Lowest | 12–20% a year, often plus warrants | Highest: a share of the company |
| Share of a typical buyout | 30–40% | 10–20% | 30–50% |
| Who provides it | Banks and direct lenders | Mezzanine funds, credit managers, SBICs | Owners, private equity firms |
Unitranche: one loan that blends senior and junior debt into a single facility. Churchill, Brightwood and CVI offer it alongside mezzanine.
Sources: cost and capital shares from Corporate Finance Institute, CAIS and Wall Street Prep.
When companies use mezzanine financing
Buyouts: a private equity firm adds mezzanine on top of the bank loan to pay for an acquisition with less equity. Nordic Mezzanine runs dedicated mezzanine funds for buyouts.
Growth and acquisitions: a profitable company borrows to expand without selling shares. Indigo Capital and ActoMezz back privately owned companies this way.
Recapitalisations: owners take money out or refinance existing debt while keeping control.
Real estate and infrastructure: mezzanine loans sit behind the mortgage or project loan. Harbor Group International lends mezzanine to real estate sponsors; Schroders Capital lends junior infrastructure debt.
How to find mezzanine lenders for a deal
Start with the debt funds: the debt funds list holds credit managers that write mezzanine next to senior loans. The wider market is covered in our guide to private credit funds and firms; how the loans work and what they pay, in what is private credit.
Add private equity firms: 37 of the 59 mezzanine lenders are tagged as private equity, not debt funds, so search the private equity list too.
Filter by cheque and region: in search, filter by cheque size, sector and headquarters. A $5M mezzanine loan and a $100M one come from different firms.
Check who just raised: a fund that closed recently has money to deploy. The new funds tracker lists each fund as it is announced.
Reach the team: profiles list partners and investment staff with their roles. CSV export comes with the Pro+ plan.
Other debt: venture-backed companies borrow from venture debt lenders; larger buyout loans come from private credit funds and firms.
Data and methodology
Firms: the 59 lenders are Private Equity List profiles whose description says they provide mezzanine, junior or subordinated debt, checked one by one on 31 October 2026. A debt-fund tag alone was not enough: 37 of the 59 are listed as private equity.
Headquarters and cheque size: as on each firm's profile.
Funds: fund records in Private Equity List and verified announcements from its new-funds tracker; sizes as recorded.
Costs and terms: not Private Equity List data; every figure links to its source.
Find mezzanine lenders
Debt funds and private equity firms that write mezzanine, with investment-team contacts and cheque sizes.
See debt funds
 Updated weekly
 Investors